
How Much Does a Breast Reduction Cost with Insurance in 2026?
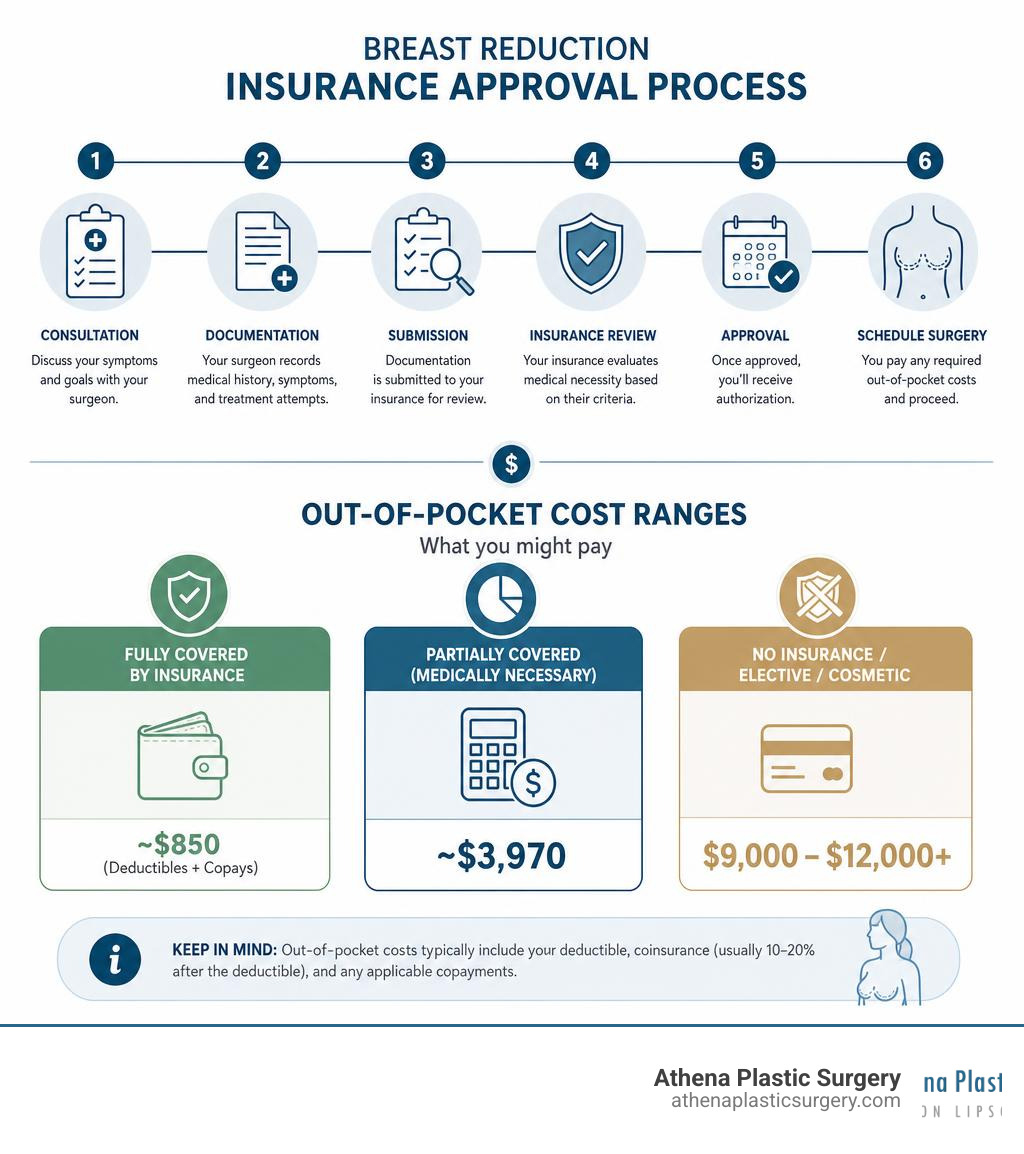
How much does a breast reduction cost with insurance is one of the most important questions women ask before pursuing this life-changing procedure. The short answer: it depends on your insurance plan, but here is a quick breakdown:
| Coverage Scenario | Typical Out-of-Pocket Cost |
|---|---|
| Fully covered by insurance | ~$850 (deductibles + copays) |
| Partially covered (medically necessary) | ~$3,970 |
| No insurance / elective / cosmetic | $9,000 – $12,000+ |
The key factor: Insurance only covers breast reduction when it is deemed medically necessary — meaning your symptoms (like chronic back pain, skin rashes, or posture problems) must be documented and meet your plan’s criteria.
Even with full approval, you will still pay something out of pocket. That typically includes:
- Your annual deductible (often $500 – $3,500)
- Coinsurance (usually 10–20% after the deductible)
- Any applicable copayments
The good news? When insurance covers the procedure, most patients pay a small fraction of the total surgical cost.
I’m Dr. Avron Lipschitz, MD, a Johns Hopkins-trained, board-certified plastic surgeon with over 15 years of experience performing breast reduction surgery. Having guided countless patients through the question of how much does a breast reduction cost with insurance, I understand both the clinical and financial sides of this decision — and I am here to help you navigate both with confidence.

Understanding How Much Does a Breast Reduction Cost with Insurance
Navigating health insurance can feel like trying to solve a puzzle in a foreign language. However, understanding a few key terms makes it much easier to estimate your potential out-of-pocket expenses.
When we look at how much does a breast reduction cost with insurance, your final bill is rarely a single flat fee. Instead, it is determined by the specific framework of your health insurance policy:
- Deductible: This is the amount of money you must pay out of pocket for healthcare services before your insurance plan starts to pay. If you have a $2,000 deductible and have not used any medical services this year, you will need to pay that first $2,000 of the surgical fees.
- Copayment (Copay): A fixed amount you pay for a specific healthcare service or visit (for example, a $50 copay for specialist consultations).
- Coinsurance: Your share of the costs of a covered health care service, calculated as a percentage. For instance, if your coinsurance is 20%, you pay 20% of the allowed surgical costs, and your insurance covers the remaining 80%.
- Out-of-Pocket Maximum: This is the most you will have to pay for covered services in a plan year. Once you reach this limit through deductibles, copays, and coinsurance, your health insurance plan pays 100% of your covered benefits.
According to the GoodRx Guide on Breast Reduction Costs, patients who successfully secure insurance coverage often see their surgical bills reduced to a fraction of the self-pay rate. However, to access these benefits, you must strictly follow your carrier’s pre-authorization guidelines. For a deeper look at how our practice handles these insurance relationships, you can read More details on insurance coverage.
Criteria for Insurance Coverage and Medical Necessity
To get your health insurance provider to cover your reduction, you must prove that the surgery is not cosmetic, but rather reconstructive and medically necessary. Cosmetic surgeries are performed to enhance appearance, while medically necessary procedures are performed to treat a diagnosed medical condition or physical symptom.
Most insurance companies look for a documented history of physical symptoms that have not responded to conservative treatments. These symptoms typically include:
- Chronic, debilitating pain in the back, neck, and shoulders
- Deep, painful grooving in the shoulders from bra straps supporting heavy breast weight
- Persistent skin rashes, chafing, or yeast infections under the breast fold (intertrigo)
- Postural problems or nerve issues, such as numbness in the hands or fingers (paresthesia)
Before approving surgery, insurance carriers generally want to see that you have tried “conservative,” non-surgical treatments for at least three to six months without success. To understand what qualifies as a strong medical case for this procedure, you can read about the clinical Reasons to Get Breast Reduction.
To help visualize how insurance companies draw the line, we have compiled the general differences in criteria:
| Medical Necessity (Often Covered) | Cosmetic/Elective (Not Covered) |
|---|---|
| Documented chronic physical pain (back, neck, shoulders) | Desire to change breast shape or size for aesthetic balance |
| Severe skin rashes under the breast fold unresponsive to creams | Fit of clothing or athletic wear without physical pain |
| Shoulder grooving and posture issues | Mild asymmetry without physical symptoms |
| Minimum tissue removal requirements met (Schnur Scale) | Patient requests a minor reduction below the insurance threshold |
| Failed conservative therapies (physical therapy, chiropractic care) | No history of non-surgical treatments |
To dive deeper into standard pricing structures and national benchmarks, you can check the ASPS Breast Reduction Cost Guide.
How Much Does a Breast Reduction Cost with Insurance for Back Pain?
Chronic back, neck, and shoulder pain is the most common reason patients seek our help. When heavy breasts place a constant, forward-pulling strain on the spine, it alters your natural posture and forces the muscles in your upper body to work overtime. Over years, this can lead to chronic musculoskeletal issues.
If you are seeking a reduction primarily to resolve back pain, your insurance company will want to see clinical documentation of your struggles. This means your medical file should include:
- Detailed notes from your primary care physician regarding your pain
- Records or letters from a chiropractor or physical therapist showing you underwent therapy to resolve the pain
- X-rays or orthopedic evaluations if your posture has been significantly impacted
Having a well-documented paper trail is the single most effective way to secure coverage. For more details on how reducing breast mass can relieve spinal strain, read our guide on Breast Reduction for Back Pain and learn how we help patients Alleviate Back Shoulder Pain Breast Reduction.
How Much Does a Breast Reduction Cost with Insurance Based on the Schnur Scale?
Even if you have documented back pain, most insurance companies use a mathematical formula called the Schnur Sliding Scale to make their final coverage decision.
The Schnur Scale calculates your Body Surface Area (BSA) using your height and weight. It then matches your BSA to a minimum weight of breast tissue (measured in grams) that the surgeon must remove from each breast during the procedure.
- The Rule: If the calculated amount of tissue to be removed is above the Schnur Scale threshold for your body size, the insurance company will likely deem the procedure medically necessary and cover it.
- The Catch: If the surgeon removes less than the required grams, the insurance company may retroactively deny coverage, leaving you with the bill.
This scale can sometimes create a dilemma. If a patient is petite but has very heavy breasts, they easily meet the threshold. However, if a patient has a higher body surface area but only needs a moderate reduction to achieve physical relief, the Schnur Scale might require the surgeon to remove more tissue than is aesthetically pleasing or safe for the patient’s frame.
Understanding these nuances is essential to determining if you are a candidate. To evaluate your personal situation, read our article on Am I a Good Candidate for Breast Reduction.
Factors That Influence the Total Cost of Surgery
If your insurance does not cover the procedure, or if you are responsible for a portion of the costs through your deductible and coinsurance, several factors will influence the total price of your surgery:
- Surgeon’s Experience and Credentials: Highly skilled, board-certified plastic surgeons who have completed specialized fellowships (such as training at Johns Hopkins) generally command higher fees. This experience is an investment in your safety and the aesthetic quality of your results.
- Geographic Location: The cost of medical care varies widely by region. Surgical fees in metropolitan areas or high-cost-of-living regions like South Florida (including West Palm Beach and Stuart) reflect the local economic landscape. You can explore regional differences via the Sidecar Health Cost by State directory.
- Type of Surgical Facility: Performing surgery in a major hospital operating room is typically more expensive than utilizing a private, accredited ambulatory surgery center (ASC). ASCs often offer savings of 30% to 50% on facility fees while maintaining top-tier safety standards.
- Anesthesia Fees: Breast reductions are performed under general anesthesia, which requires a certified anesthesiologist or nurse anesthetist (CRNA). Their fees are billed separately and are based on the duration of the surgery.
- Surgical Technique: The complexity of your procedure—whether you require a traditional anchor incision (inverted-T), a vertical “lollipop” incision, or liposuction-assisted reduction—will affect the surgical time and overall cost.
For a comprehensive breakdown of the entire surgical journey, from the initial consultation to the final recovery phase, read our Breast Reduction Surgery Complete Guide.
Frequently Asked Questions About Breast Reduction Costs
Navigating the financial and clinical steps of a breast reduction can bring up many questions. Below are some of the most common queries we receive from patients in our Stuart and West Palm Beach communities.
Does insurance cover a breast lift combined with a reduction?
A standard breast reduction inherently includes a breast lift. When we remove excess skin, fat, and glandular tissue, we must reposition the nipple-areola complex higher on the breast mound to create a natural, youthful, and proportionate shape. Therefore, you do not need to pay extra for a “lift” when undergoing a medically necessary breast reduction; the lifting and reshaping are structural components of the reduction itself.
However, if you do not meet the medical necessity criteria for a reduction and are primarily seeking to lift sagging breasts (mastopexy) without removing significant tissue volume, insurance will classify the procedure as cosmetic and will not cover it. To learn more about achieving a balanced, comfortable silhouette, read about how you can Enjoy Proportionate Figure Breast Reduction.
What documentation is required for insurance approval?
To build a strong case for medical necessity, you should compile a comprehensive “insurance approval packet.” We recommend gathering the following documentation:
- Primary Care Physician (PCP) Letters: A detailed letter from your doctor outlining your physical symptoms, their duration, and how they limit your daily activities.
- Specialist Records: Notes, treatment plans, and progress reports from physical therapists, chiropractors, or orthopedists showing at least 3 to 6 months of conservative care.
- Prescription History: Records of any prescribed anti-inflammatory medications, muscle relaxants, or topical skin creams used to treat rashes under the breasts.
- Clinical Photographs: Our office will take professional, medical-grade photographs (focusing on shoulder grooving and breast posture) to submit directly to your carrier.
What financing options are available if insurance doesn’t cover the full cost?
If your insurance plan excludes breast reduction, or if you have a high deductible that feels overwhelming, several healthcare financing options can help make the investment manageable:
- Medical Credit Cards: Programs like CareCredit and Alphaeon offer specialized financing plans, often featuring 0% interest promotional periods for 6 to 24 months for qualified borrowers.
- In-House Payment Plans: Many plastic surgery practices partner with healthcare lending platforms to offer structured monthly installment plans.
- HSA and FSA Accounts: Because a medically necessary breast reduction treats a diagnosed physical issue, you can often use pre-tax dollars from your Health Savings Account (HSA) or Flexible Spending Account (FSA) to pay for your out-of-pocket expenses.
Conclusion
At Athena Plastic Surgery, we believe that physical comfort and self-confidence should not be out of reach due to financial confusion. Led by Johns Hopkins-trained plastic surgeon Dr. Avron Lipschitz, our team is dedicated to providing compassionate, top-tier care to patients throughout Stuart and West Palm Beach, FL.
We understand that every patient’s body and insurance policy are completely unique. While general estimates can help you begin your research, the only way to get an accurate, customized price quote—and to determine if you meet the clinical criteria for insurance coverage—is through a private, one-on-one evaluation. We will work closely with you to document your symptoms, navigate your carrier’s requirements, and design a customized surgical plan tailored to your health and aesthetic goals.
Ready to take the first step toward physical relief? Schedule a consultation for breast reduction and reconstruction with us today, and let us help you live life comfortably.