
Making Your Dream Surgery Financially Achievable
Breast implants financing options can transform a distant wish into a realistic plan. A typical breast augmentation in Canada costs $10,000–$13,000, but you don’t have to produce that sum all at once.
Key ways patients spread out the cost:
- Specialized medical-financing companies – streamlined applications, payments from roughly $98–$185/month
- Personal loans – competitive rates if you have strong credit
- Credit cards – useful for 0 % promotional periods when paid off quickly
- In-house payment plans – some clinics let you pay the balance over time
- Lines of credit – flexible borrowing against existing credit limits
Terms generally range from 6 months to 7 years, with interest between 3.99 % and 30.99 % based on credit history.
Many people postpone surgery because a single upfront payment feels impossible. With thoughtful planning, you can choose a repayment schedule that fits comfortably into your budget.
As Dr. Avron Lipschitz, Board-Certified Plastic Surgeon, I’ve guided thousands of patients through their financial options so they can focus on their surgical journey with confidence.

The Real Price Tag: Breaking Down Breast Augmentation Costs
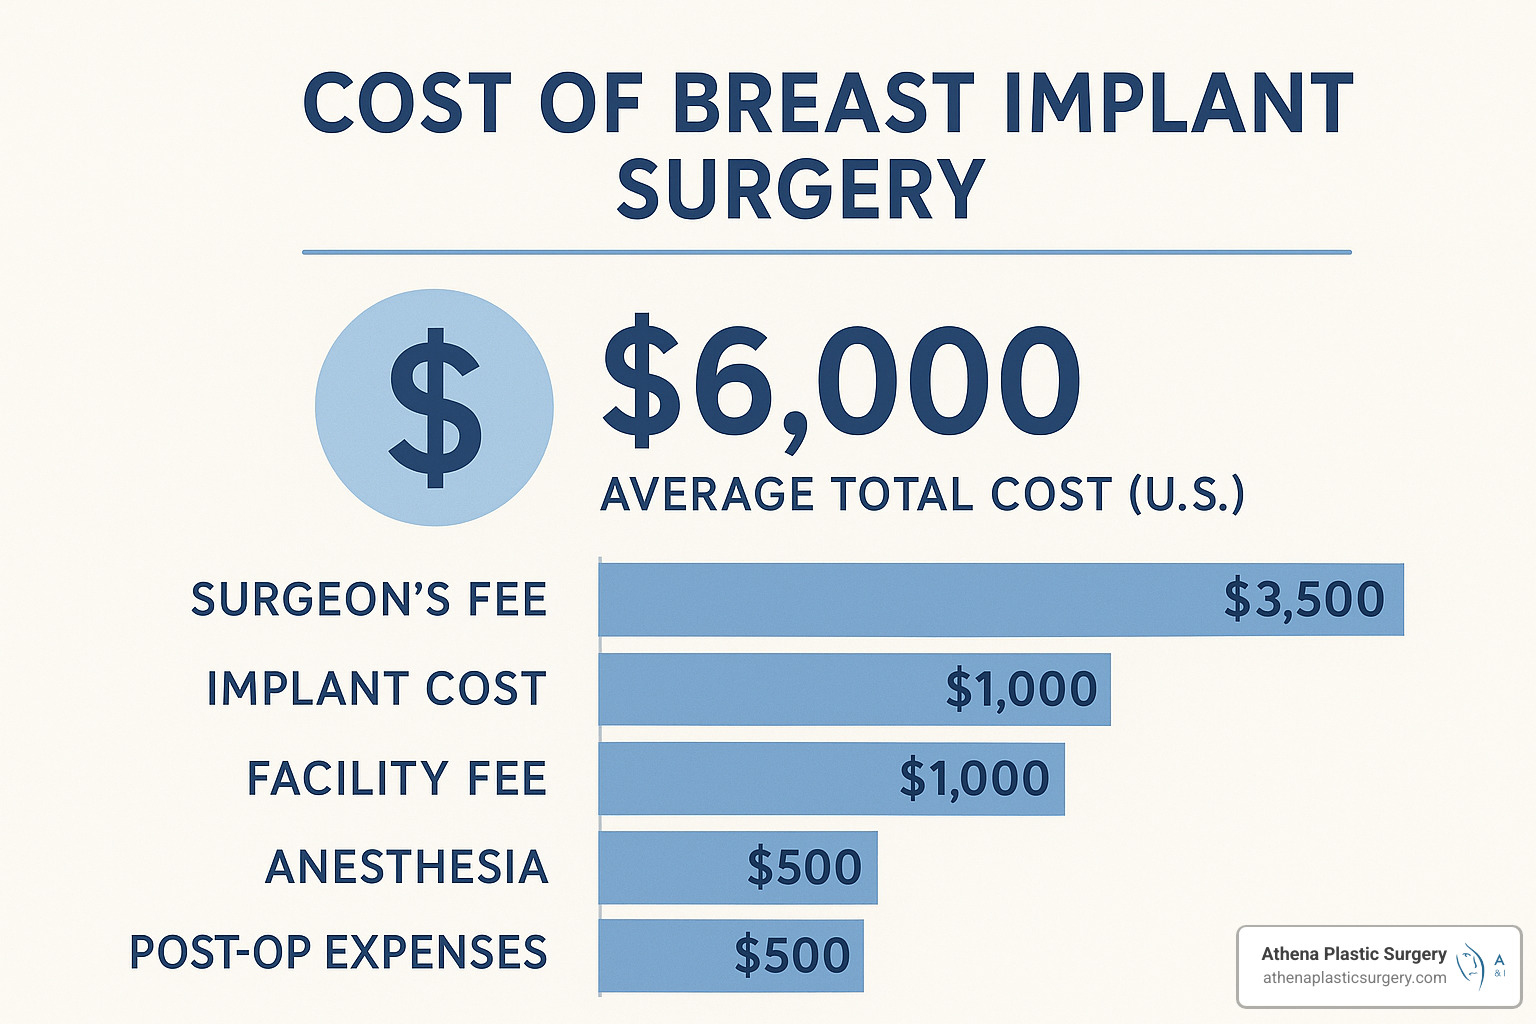
Before exploring breast implants financing options, you need to understand what you’re actually paying for. That $10,000-$13,000 price tag might seem overwhelming at first glance, but it’s helpful to see how this investment breaks down into specific components.
Think of breast augmentation costs like building a house—there’s the architect, materials, construction crew, and finishing touches. Your surgeon’s fee typically represents the largest portion at $5,000-$8,000, reflecting years of specialized training and expertise. This isn’t just about the two hours in surgery; it includes pre-operative planning, the procedure itself, and post-operative care.
The implant cost ranges from $1,500-$2,500, with silicone implants commanding higher prices than saline due to their more natural feel and advanced manufacturing. Your facility fee of $1,500-$2,000 covers the operating room, specialized equipment, and support staff who ensure your safety throughout the procedure.
Don’t forget the anesthesia fee of $800-$1,200—this covers your anesthesiologist’s expertise in keeping you comfortable and safe during surgery. The consultation fee typically runs $200-$250, though at Athena Plastic Surgery, we credit this toward your procedure cost if you schedule surgery within six months. Finally, post-operative garments like compression bras cost $100-$200 but play a crucial role in your healing process.
Geographic location affects pricing significantly. Procedures in major Canadian cities like Toronto typically range from $9,000 to $14,750, while smaller centers may offer slightly lower costs. However, choosing a surgeon based solely on price can be risky—experience and credentials should guide your decision.
At Athena Plastic Surgery, we believe in complete transparency. During your consultation, you’ll receive a detailed breakdown of every cost, so there are no surprises when exploring your financing options.
Hidden and Ongoing Expenses You Should Budget For
Smart financial planning means preparing for costs that many patients don’t initially consider. We’ve seen too many women caught off-guard by expenses they didn’t anticipate, so let’s address them upfront.
Time off work often represents the biggest hidden cost. Plan for 1-2 weeks away from work, which could mean unpaid leave if you don’t have accumulated sick days. Self-employed patients need to factor in reduced earning capacity during recovery.
Prescription medications for pain management and infection prevention typically cost $100-$200. Scar care products like silicone sheets or specialized gels add another $50-$150 to your budget, but they’re worth the investment for optimal healing.
You’ll also need special supportive bras during recovery, which can cost $200-$400. These aren’t your regular bras—they’re designed specifically for post-surgical support and comfort.
While rare, revision surgery sometimes becomes necessary. It’s wise to budget an additional 5-10% of your original procedure cost as a safety net, even though most patients never need it.
Many patients find household help invaluable during recovery. Meal delivery services, cleaning help, or extra childcare might not be medically necessary, but they can significantly improve your comfort and healing experience. These lifestyle supports vary widely in cost but are worth considering as part of your overall financial planning.
Breast Implants Financing Options: What Choices Do You Have?
A $10,000 procedure rarely sits untouched in anyone’s savings account. Understanding your breast implants financing options helps you act sooner rather than “someday.”
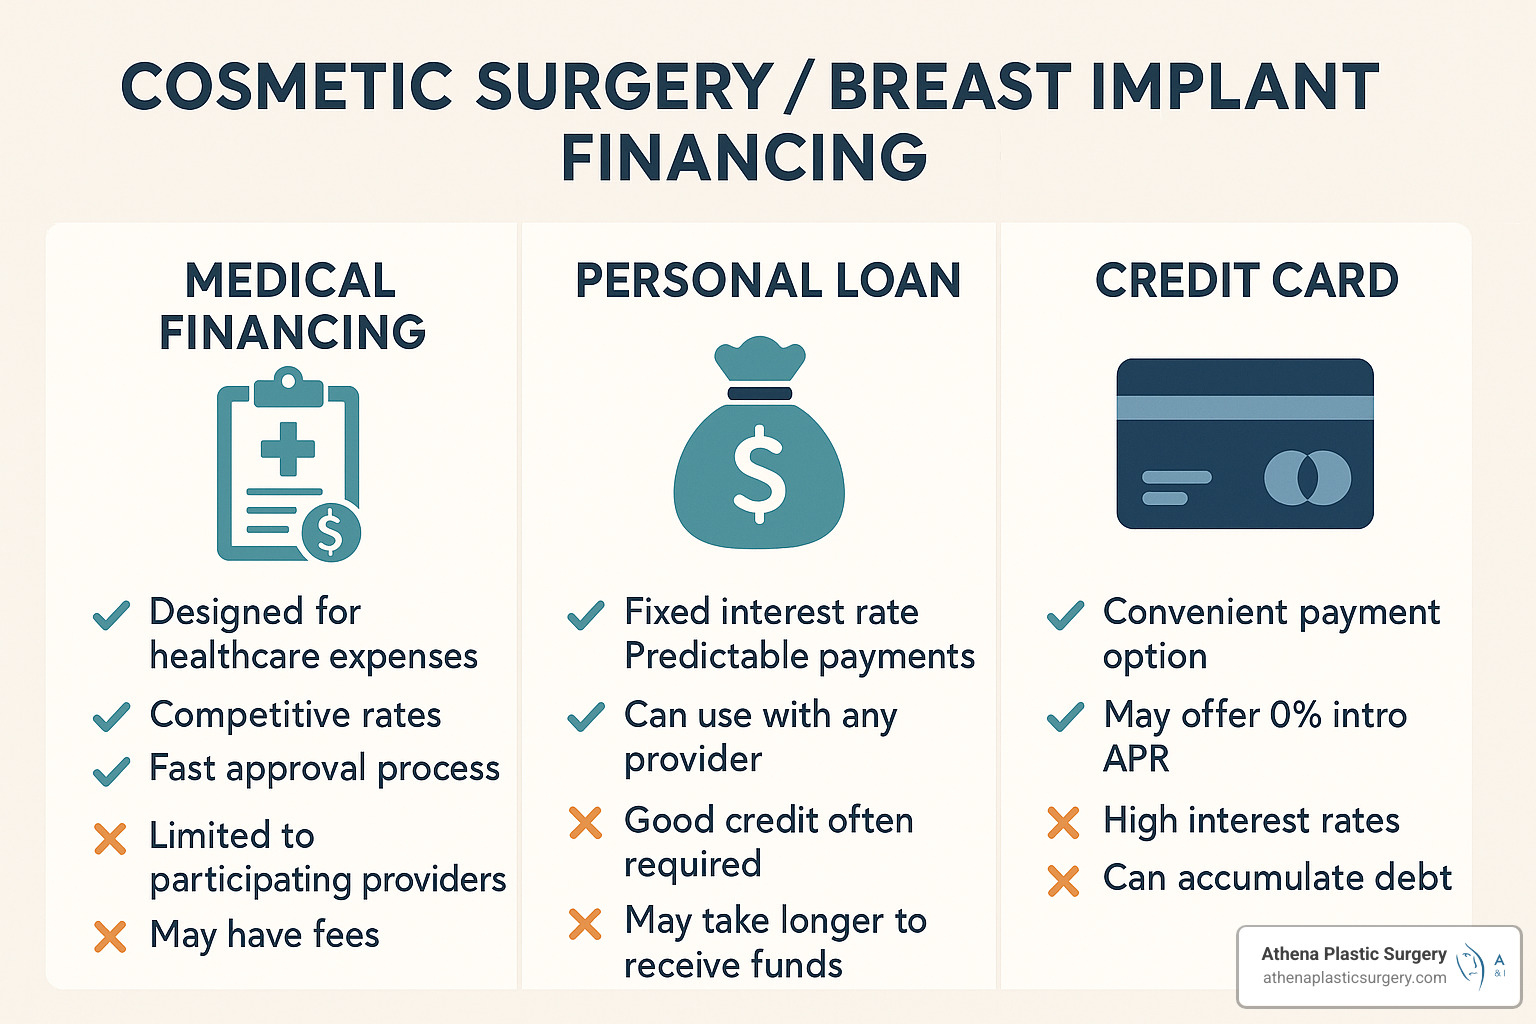
Common routes include:
- Medical-financing lenders – purpose-built for healthcare expenses and often more flexible than banks.
- Personal loans – lump-sum funding, fixed payments, usually best for good credit.
- Credit cards – excellent when paired with 0 % intro rates and disciplined payoff.
- Lines of credit – draw what you need, repay only what you use.
- In-house payment plans – select clinics may offer short-term schedules after a deposit.
At-a-Glance Numbers
Loan amounts typically $1,500–$25,000, interest 3.99–30.99 % APR, and terms 6 months to 7 years. For a $10,000 loan, payments can start around $185/month (5-year term, mid-range rate). A comparable personal loan at 8 % over 5 years costs roughly $203/month.
Pros & Cons Snapshot
Medical financing offers quicker approvals and direct payment to your surgeon, but rates rise sharply if promo periods expire. Personal loans may deliver lower total interest, yet application requirements are stricter. Credit cards give instant access but can snowball if you carry a balance long-term.
Match the option to your financial habits: fixed payments for planners, revolving credit for disciplined payoffs, or purpose-built medical loans if you value speed and simplicity.
How Dedicated Medical Financing Works
Medical-specific lenders fill the gap traditional banks often ignore. They provide no-collateral, no-down-payment loans that are paid directly to your surgical practice, allowing you to schedule promptly and focus on recovery instead of invoices.
Quick Application & Eligibility
- Secure 10-minute online form
- Instant pre-approval decision (soft credit check)
- Upload proof of income and ID
- Final approval in 1–3 business days
- Funds sent straight to the clinic
Basic requirements: 18 + years old, Canadian or U.S. resident, verifiable income.
Typical Rates & Terms
- Interest: approx. 4 %–30 % depending on credit
- Loan amounts: $1,500–$25,000
- Repayment: 6 months–7 years
- No pre-payment penalties
Example: Borrow $10,000 at 12 % APR
- 2 years – $470/month (total $11,280)
- 5 years – $222/month (total $13,320)
Automatic payments often shave 0.25–0.50 % off the rate and guarantee you never miss a due date.

From Approval to First Payment: Managing Your Loan Responsibly
Congratulations! You’ve been approved for financing. Now comes the important part—managing your loan in a way that supports both your surgical journey and your financial health.
The first step is creating a realistic budget that comfortably accommodates your new monthly payment. Your loan payment shouldn’t feel like a financial burden that causes stress during your recovery. As a general rule, keep your payment under 10-15% of your take-home income to maintain breathing room in your budget.
Use online payment calculators to see exactly how different loan terms affect your monthly obligations. A $10,000 loan over 3 years might cost $300 monthly, while the same amount over 5 years drops to around $200. Choose terms that align with your comfort level—there’s no shame in taking longer to pay if it means better financial stability.
Setting up automatic payments is one of the smartest moves you can make. You’ll never miss a due date, which protects your credit score and often earns you an interest rate discount from your lender. Most companies let you choose your payment date, so pick one that works with your pay schedule—maybe a few days after your paycheck arrives.
Many patients find it helpful to track their loan progress over time. Some people love watching their balance decrease each month, while others prefer to set up autopay and focus on other things. Both approaches work fine—choose whatever feels right for your personality.
Your financial situation might change during your repayment period, and that’s completely normal. If your credit score improves significantly or market rates drop, consider refinancing your loan. You might qualify for better terms that save you money. Just make sure to factor in any refinancing fees before making the switch.
Life has a way of throwing curveballs, so it’s important to plan for potential changes. Job loss, medical emergencies, or other financial challenges can affect your ability to make payments. If you ever anticipate difficulty making a payment, contact your lender immediately. Most companies are willing to work with you if you communicate proactively rather than simply missing payments.
One thing to keep in mind: cosmetic surgery generally isn’t tax-deductible in Canada unless it’s medically necessary. The interest on your breast implants financing options typically won’t be deductible either. If you have questions about your specific tax situation, it’s worth consulting with a tax professional.
Safeguards & Red Flags When Financing Cosmetic Surgery
Not all financing offers are created equal, and unfortunately, some companies prey on people’s desire to improve their appearance. Here’s how to protect yourself from predatory lending practices.
High APR rates above 35% should raise immediate red flags. While medical financing rates vary based on credit scores, extremely high rates often indicate predatory lending. Similarly, watch out for balloon payments where you make small payments initially but owe a large lump sum at the end—these can create serious financial problems down the road.
Be wary of excessive origination fees that add more than 5% to your loan amount. Some fees are normal, but excessive charges eat into your surgical budget unnecessarily. Any lender that pressures you to sign immediately without giving you time to review the terms is also concerning—legitimate companies want you to understand your commitment.
Unclear terms or hidden fees buried in fine print are another warning sign. Your financing agreement should be straightforward and easy to understand. If you need a law degree to interpret the terms, look elsewhere.
The responsibility extends beyond just financing—you also need to be careful about your clinic’s reputation and credentials. Make sure your surgeon is board-certified in plastic surgery and that your surgical facility meets proper safety standards. At Athena Plastic Surgery, Dr. Avron’s Johns Hopkins training and our commitment to patient safety ensure you’re in qualified hands.
We work with multiple financing partners specifically so you have options and aren’t pressured into any single arrangement. We believe informed decisions lead to better outcomes, both surgically and financially.
Remember this simple rule: if a financing offer seems too good to be true, it probably is. Legitimate breast implants financing options should be transparent, competitive, and designed to help you achieve your goals without creating financial hardship. Trust your instincts—if something feels off, take time to research other options.
Your breast augmentation is an investment in yourself, and the financing should support that investment, not undermine your financial stability. Take the time to choose wisely, and you’ll be able to enjoy your results without financial stress.
Frequently Asked Questions About Breast Implants Financing Options
How quickly can I get approved and access funds?
The beauty of modern medical financing is how fast everything moves. When you’re excited about your breast augmentation journey, waiting weeks for loan approval feels like forever. Thankfully, that’s not how it works anymore.
Most medical financing companies give you an instant answer right during your online application. It’s pretty amazing—you fill out the form, hit submit, and within minutes you know if you’re pre-approved. No sitting by the phone or checking your email obsessively.
The full approval process typically wraps up in 1-3 business days once you submit your documents. Here’s how it usually flows: you get that instant pre-approval, then spend a day gathering your pay stubs and bank statements. Upload everything through their secure portal, and within 24-48 hours, you have final approval with your exact terms.
The money reaches your surgeon within 1-3 business days after final approval. Most patients complete the entire journey—from first application click to surgeon payment—within the same week.
I always tell my patients to apply for financing about a week before their desired surgery date. This gives you a comfortable buffer for any unexpected hiccups, though they’re rare with established lenders.
Your approval speed often depends on how prepared you are. Patients with excellent credit who upload complete documentation right away typically see the fastest processing. Having your financial paperwork organized before you start makes everything smoother.
Can I finance only a portion of my procedure?
This is one of my favorite questions because it shows patients are thinking strategically about their finances. You absolutely have complete control over how much you finance versus pay upfront.
Many of my patients choose what I call the “hybrid approach.” Maybe you’ve been saving for a few years and have $4,000 set aside, but your breast augmentation costs $12,000. Perfect—pay the $4,000 upfront and finance the remaining $8,000. This reduces your monthly payments while still making the procedure totally doable.
Some patients get creative with their payment strategy. They might finance just the surgeon’s fee (usually the largest component) while paying the facility and anesthesia costs out of pocket. Others prefer to finance everything surgical but handle their post-op garments and medications separately.
At Athena Plastic Surgery, we credit your $200 consultation fee toward your procedure if you schedule surgery within six months. Many patients factor this into their financing calculations—it’s a nice little reduction in what you need to borrow.
The key is choosing what works for your budget and peace of mind. There’s no “right” amount to finance. I’ve had patients finance as little as $3,000 and others who finance the full procedure cost. Your financial comfort matters more than any arbitrary rules.
Does my credit score affect the rate I receive?
Your credit score definitely impacts your interest rate, but don’t let that discourage you if your credit isn’t perfect. Medical financing companies often work with patients across the credit spectrum because they understand that creditworthiness doesn’t always reflect someone’s commitment to important healthcare decisions.
Here’s roughly how credit scores translate to rates: Patients with excellent credit (750+) typically qualify for the lowest advertised rates, often between 3.99%-8.99%. Good credit (650-749) usually means moderate rates around 8.99%-15.99%. Fair credit (550-649) might see rates of 15.99%-25.99%, and credit below 550 often faces the highest rates of 25.99%-30.99%.
But here’s what many patients don’t realize—even with less-than-perfect credit, you can still get approved. I’ve worked with patients across all credit ranges who successfully financed their procedures. Medical financing companies understand that healthcare is a priority, and they’re often more flexible than traditional lenders.
If your credit score is borderline, you have options. Consider adding a cosigner with good credit, or spend a few months improving your score before applying. Sometimes waiting 3-6 months while paying down credit card balances can save you thousands in interest over your loan term.
Pro tip: Check your credit report for errors before applying. I’ve seen patients find mistakes that, once corrected, improved their scores by 50+ points. That kind of improvement can significantly impact your rate and save you real money.
The most important thing? Don’t let credit concerns stop you from exploring your options. Many patients are pleasantly surprised by what they qualify for.
Conclusion
Your dream of breast augmentation shouldn’t hinge on a single lump-sum payment. With today’s breast implants financing options, you can plan a procedure that aligns with both your aesthetic and financial goals.
The most successful patients approach financing with clear expectations—budgeting not just for surgery day but also for time off work, medications, and follow-up visits. The lowest monthly payment isn’t automatically the smartest choice; balance affordability with total interest paid.
Athena Plastic Surgery partners with respected lending platforms so we can tailor solutions to your unique circumstances. Dr. Avron Lipschitz and our team will walk you through realistic cost projections, helping you pick a payment plan that feels empowering, not stressful.
Ready to explore your options? Visit our complete guide here: More info about Financing. We’re here to support every step of your surgical and financial journey.