
The Critical Difference Between Cosmetic and Functional Surgery
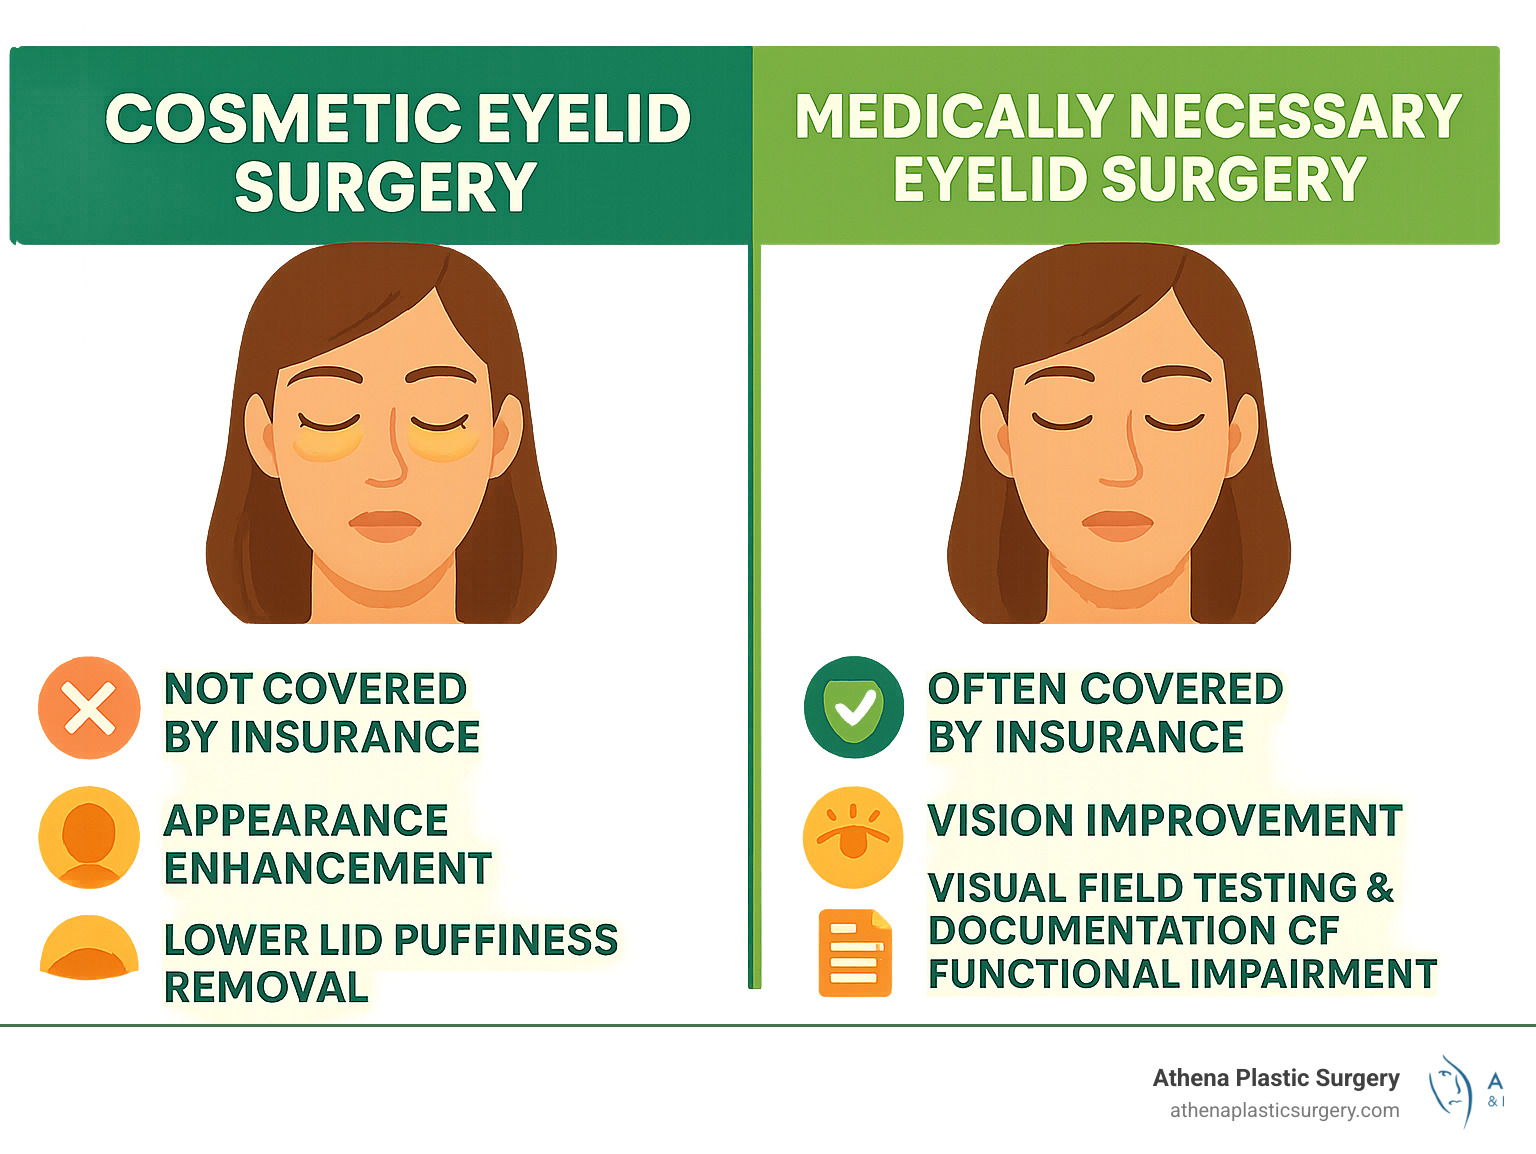
Whether eyelid surgery covered by insurance is possible depends on if your procedure is medically necessary or purely cosmetic. Understanding this distinction can save you thousands of dollars and help you steer the approval process.
Quick Answer: When Insurance Covers Eyelid Surgery
- Upper eyelid surgery – Often covered when drooping skin blocks vision.
- Lower eyelid surgery – Rarely covered unless related to specific medical conditions.
- Required proof – Visual field testing showing at least 30% vision loss that improves with taping.
- Key measurement – Eyelid margin within 2mm of the pupil’s center.
- Documentation needed – Photos, visual field tests, and physician notes proving medical necessity.
Insurance companies cover eyelid surgery when excess upper eyelid skin creates a “visually significant” obstruction that affects daily activities like driving or reading. However, surgery performed simply to remove puffiness or improve appearance is considered cosmetic and won’t be covered. Lower eyelid surgery usually falls into this category, as excess tissue beneath the eye rarely obstructs vision.
As Dr. Avron Lipschitz MD, I have helped countless patients steer the insurance approval process for medically necessary eyelid surgery throughout my 15+ years of practice. My experience with both functional and cosmetic procedures provides unique insight into when eyelid surgery covered by insurance is likely to be approved and how to properly document medical necessity.
Decoding Medical Necessity: When is Eyelid surgery covered by insurance?
Wondering if eyelid surgery covered by insurance is possible means you’re dealing with medical necessity. Insurers will pay if your eyelids genuinely interfere with your vision, but not just to make you look more refreshed.
Upper eyelid surgery gets approved by insurance more often than you might think. When excess skin (dermatochalasis) or a weakened eyelid muscle (ptosis) causes problems, these are not just cosmetic concerns. Some patients can’t drive safely or develop headaches from straining to see.
The story is different with lower eyelid surgery. Those under-eye bags that make you look tired rarely obstruct your vision. While they may be a cosmetic concern, insurance companies view lower blepharoplasty as almost always cosmetic. Rare exceptions exist, such as when lower lid bulk prevents wearing glasses, but this is uncommon.
Ptosis is a medical condition where the eyelid muscle weakens, causing the lid itself to droop. When your eyelid margin falls near or across your pupil, it creates a genuine visual obstruction that can significantly impact your daily life.
Insurance companies use the phrase “visually significant” obstruction. This means your eyelid issues are genuinely getting in the way of daily activities like driving, reading, or working on a computer.
| Feature | Upper Eyelid Surgery (Blepharoplasty/Ptosis Repair) | Lower Eyelid Surgery (Blepharoplasty) |
|---|---|---|
| Primary Reason for Surgery | Vision impairment, functional issues | Cosmetic improvement (bags, wrinkles) |
| Insurance Coverage Likelihood | High, if medically necessary | Very Low, almost always cosmetic |
| Common Medical Conditions | Dermatochalasis, Ptosis, Blepharospasm, Thyroid Eye Disease | Systemic conditions causing bulk affecting glasses (rare) |
| Key Proof for Coverage | Visual field tests, photos of vision obstruction | Rarely vision-related; usually no proof for coverage |
| Impact on Daily Life | Driving, reading, computer use, headaches | Aesthetic concerns, rarely functional |
| Typical Cost if Not Covered | $3,339 (average cosmetic, excluding fees) | $3,339 (average cosmetic, excluding fees) |
What specific conditions and symptoms qualify for coverage?
Several specific conditions can move your case from the “cosmetic” category into the “medically necessary” field, making eyelid surgery covered by insurance more likely.
Vision obstruction is the strongest argument. If your upper eyelid skin physically blocks your superior or peripheral vision, you’re likely a good candidate. Symptoms include difficulty driving, reading comfortably, or “brow pain” from subconsciously lifting your eyebrows to see.
Congenital conditions like ptosis often qualify, especially in children where a droopy eyelid threatens to cause amblyopia (lazy eye) or other vision development issues.
Trauma or disease reconstruction is almost always covered. If your eyelid condition resulted from an injury, thyroid eye disease, Bell’s palsy, or tumor removal, the surgery to restore normal function is considered medically necessary.
Chronic dermatitis from rubbing lashes, caused by severe excess skin, can strengthen your case if the irritation doesn’t respond to other treatments.
Painful blepharospasm, a neurological condition causing involuntary eyelid spasms, might also qualify for surgery if symptoms are severe.
The key is demonstrating that your symptoms genuinely impact your quality of life. For more details, explore our guide: More info about what blepharoplasty is.
How do insurers define ‘visually significant’ obstruction?
Insurers require objective, measurable proof that your vision is truly obstructed to get eyelid surgery covered by insurance.
Pupil obstruction is straightforward evidence. If eyelid tissue is encroaching on your pupil or resting on your eyelashes, it’s a concrete obstruction.
Margin Reflex Distance (MRD) provides a precise measurement from the center of your pupil to your upper eyelid margin. Many insurance policies require an MRD of 2 millimeters or less for ptosis repair coverage.
Superior visual field degrees come from specialized testing. Insurers typically require your superior visual field to be 30 degrees or less, with significant improvement (an increase of 12 degrees or 30%) when the eyelid is taped up to simulate surgical correction.
These measurements transform subjective complaints into objective data. Even Medicare has clearly defined criteria that experienced oculoplastic surgeons understand. The American Academy of Ophthalmology provides more insight here: American Academy of Ophthalmology on functional blepharoplasty.
The Approval Process: Documentation, Tests, and Pre-Authorization
Getting eyelid surgery covered by insurance requires proving you qualify with paperwork, evidence, and patience.
The journey starts with a thorough evaluation by a specialist, like an oculoplastic surgeon or an ophthalmologist, who understands insurance requirements. We don’t just examine your eyelids; we build a case demonstrating why the surgery is essential for your health and daily function.
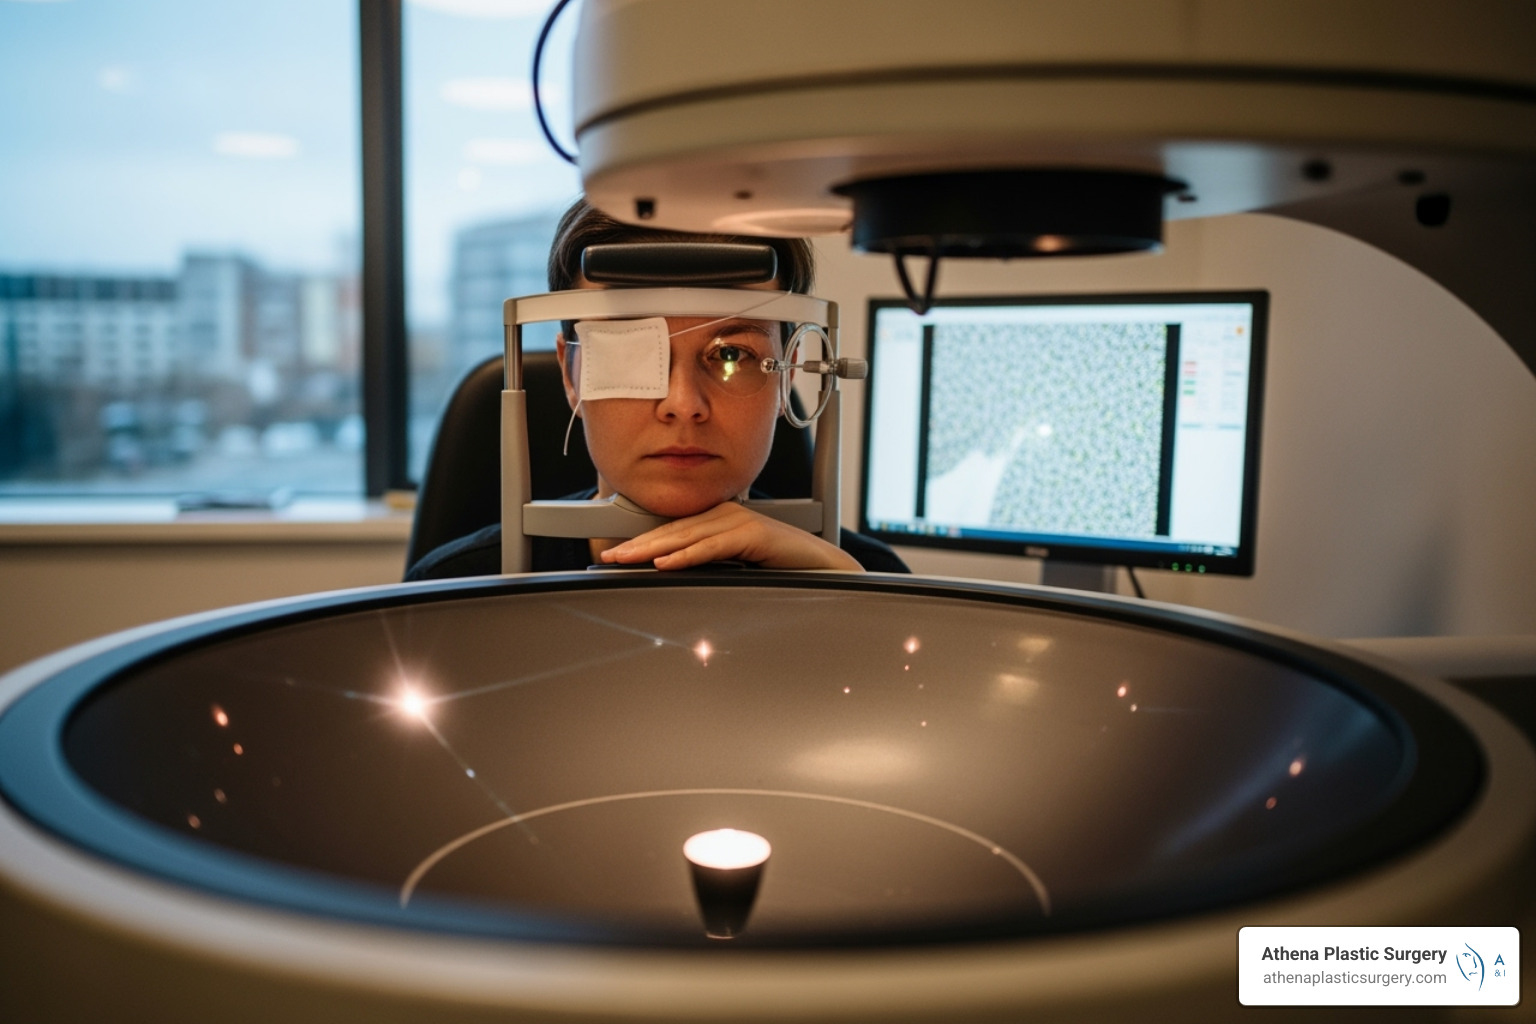
During this evaluation, we take detailed photographs, conduct specific measurements, and arrange for visual field testing. This documentation is compiled into a package that shows how your eyelids are genuinely affecting your ability to see and function.
The pre-authorization process varies. Some insurance companies require it, while others, like Medicare, do not. Pre-approval doesn’t guarantee payment, but it makes the process smoother. I always tell my patients that thorough documentation upfront is an investment that prevents surprises later.
What documentation is required for eyelid surgery covered by insurance?
For eyelid surgery covered by insurance, documentation is everything. Incomplete paperwork can lead to denial. Here’s what’s needed to build a strong case for medical necessity.
- Dated photographs (recent, within 12 months) are crucial visual evidence. We take professional, eye-level photos showing how the eyelid tissue interferes with your vision, including comparison shots with the eyelids taped up to show potential improvement.
- Visual field test results provide objective proof of vision loss. The test is done twice—with eyelids drooping and taped up—to show the improvement surgery can provide, which is compelling evidence for insurers.
- A physician’s detailed notes and letter of medical necessity form the medical foundation of your case. These documents must include specific measurements like your Margin Reflex Distance, detailed descriptions of your symptoms, and a clear explanation of how the surgery will improve your functional vision.
- A patient symptom diary provides powerful, real-world context by documenting specific instances where vision problems affect daily activities, like driving or reading.
- Some insurers also require referrals or evaluations from ophthalmologists, especially when a plastic surgeon performs the surgery, to confirm the visual impairment is genuine.
The goal is to create a comprehensive picture that proves medical necessity. Learn more about procedure differences here: how upper and lower eyelid surgery are different.
What is the crucial role of a visual field test?
The visual field test is the make-or-break component for getting eyelid surgery covered by insurance. It provides objective proof of vision loss, which is essential for approval.
This non-invasive test maps your complete field of vision, identifying how much your peripheral sight is compromised. You’ll sit in front of a specialized machine and click a button whenever you see lights appear in your peripheral vision.
The test is performed twice: once with your eyelids in their natural, drooping position, and again with them taped up. The comparison between these two results provides objective, measurable proof of how much your eyelids are blocking your vision.
Insurance companies look for specific improvements after taping, such as a 12-degree increase in superior visual fields or a 30% improvement overall. When we demonstrate these measurable improvements, it becomes very difficult for insurers to argue that the surgery isn’t medically necessary.
This test quantifies your vision loss, changing subjective complaints into hard data that insurance reviewers can evaluate objectively. It provides the objective proof that speaks directly to insurance company requirements, and without it, even the most necessary cases can face an uphill battle for approval.
Understanding the Costs and Payment Alternatives
Even when your eyelid surgery covered by insurance, you will likely have some out-of-pocket expenses. Understanding these potential costs upfront helps you plan and avoid surprises.
With insurance approval, you’ll typically encounter expenses like your deductible (the amount you pay before insurance kicks in), co-pays (fixed fees for services), and coinsurance (your percentage of the remaining costs).
The key is to get a clear picture of your financial responsibility before surgery. We encourage patients to call their insurance company to ask about their specific coverage for blepharoplasty. Our patient coordinators can also help you steer this process and provide detailed cost breakdowns.
If your insurance denies coverage or your procedure is purely cosmetic, don’t let that stop you from exploring your options. We have helped many patients find ways to make their eyelid surgery financially manageable.
What if my eyelid surgery is not covered by insurance?
When eyelid surgery is not covered by insurance, you will pay the full cost out of pocket. Many patients still find this to be a worthwhile investment in their vision and confidence.
According to the American Society of Plastic Surgeons, the average surgeon’s fee for cosmetic eyelid surgery is $3,339. However, this is just one part of the total cost. Your total cost will also include the anesthesia costs, facility fees (for the operating room, equipment, and staff), prescription medications, and any pre-operative medical tests.
We believe in complete cost transparency. During your consultation, you’ll receive a detailed breakdown of all expenses. We also offer financing options through medical financing companies that allow you to spread payments over time, making the procedure more manageable.
For comprehensive details, visit our eyelid surgery cost details page or review national statistics at the American Society of Plastic Surgeons cost statistics.
Can I use an FSA or HSA for eyelid surgery?
Yes, your Flexible Spending Account (FSA) or Health Savings Account (HSA) can be very helpful for covering expenses related to eyelid surgery covered by insurance, but there’s an important distinction.
If your eyelid surgery is medically necessary, you can use FSA or HSA funds for any out-of-pocket costs, including your deductible, co-pays, and coinsurance.
However, if your procedure is purely cosmetic, you typically cannot use these pre-tax accounts. The IRS is strict about this, and cosmetic procedures usually don’t qualify as medical expenses.
Using your FSA or HSA is a smart move when possible because you’re paying with pre-tax dollars, which is like getting a discount equal to your tax bracket.
Always check with your specific plan administrator before assuming coverage, as some plans have unique rules. HSA funds roll over year after year, so you can save for procedures. FSAs often have a “use it or lose it” policy, though many now offer a small rollover amount or a grace period.
Frequently Asked Questions about Insurance for Eyelid Surgery
Navigating insurance can be confusing, especially when trying to get your eyelid surgery covered by insurance. It’s normal to have questions. Here, we answer some of the most common inquiries to help make things clearer.
Does Medicare cover eyelid surgery?
Yes, Medicare can cover eyelid surgery like upper eyelid blepharoplasty or ptosis repair, but it must be deemed medically necessary. Like private insurers, Medicare has very specific criteria to prove that your drooping eyelids are causing a functional vision problem.
Many private insurance companies model their coverage criteria after Medicare’s guidelines, so the requirements for visual field testing, photos, and objective measurements are often consistent.
One unique aspect of Medicare is that it generally doesn’t offer pre-authorization. This means we can’t get a definitive “yes” before surgery. However, an experienced oculoplastic surgeon like Dr. Avron is deeply familiar with Medicare’s criteria and can give you a strong sense of whether your case will likely be covered.
Because there’s no pre-authorization, you might be asked to sign an Advance Beneficiary Notice (ABN) if there’s a chance your procedure might not meet the strict rules. An ABN is a notice confirming you understand that if Medicare denies the claim, you will be responsible for the cost.
Medicare’s criteria for functional impairment are strict, typically requiring: documented visual obstruction affecting daily activities, objective measurements showing the eyelid is very close to or covering the pupil (often within 2mm), and visual field tests demonstrating significant vision loss with noticeable improvement after taping.
If you’re a Medicare beneficiary, our team will help ensure all necessary documentation is gathered and submitted to give you the best chance for coverage.
Who should perform the evaluation for insurance purposes?
To get the best chance of having your eyelid surgery covered by insurance, the evaluation and documentation should be handled by a specialist in eyes and the surrounding structures.
- Oculoplastic Surgeon: This is often the gold standard. They are ophthalmologists with additional training in plastic and reconstructive surgery of the eyelids. Their dual expertise in function and aesthetics makes them uniquely qualified. Dr. Avron is a Johns Hopkins-trained oculoplastic surgeon.
- Ophthalmologist: An eye M.D. who can conduct the necessary tests to confirm vision impairment.
- Board-Certified Plastic Surgeon: A plastic surgeon with significant experience in eyelid procedures can also perform the evaluation, provided they are familiar with insurance documentation requirements.
A specialist’s evaluation is crucial because they know what insurers require: objective measurements, clear photos, and detailed notes that strengthen your claim by explaining the medical necessity.
What happens if my insurance claim is denied?
If your initial claim for eyelid surgery covered by insurance is denied, don’t lose hope. Denials are common and can often be successfully appealed. Think of it as a request for more information.
Here are the steps to take if you receive a denial:
- Review the Denial Reason: First, understand exactly why the claim was denied. The insurer must provide a reason, such as missing documentation or not meeting specific criteria.
- Gather More Evidence: Based on the denial reason, collect more information. This could include more detailed physician notes, additional photos, a patient symptom diary, or a second opinion.
- Understand the Appeals Process: Your denial letter will outline the appeal steps. This usually involves an Internal Appeal directly to the insurer, followed by an External Review by an independent third party if the internal appeal fails.
- Submit a Formal Appeal Letter: Write a clear letter that references your policy and claim numbers, states you are appealing, explains why the surgery is medically necessary, lists enclosed documents, and requests a new review.
- Be Persistent and Keep Records: The appeals process takes time. Follow up regularly and keep detailed records of all communications. Persistence often pays off.
Our team at Athena Plastic Surgery is here to support you through this process. We can help you gather the necessary documentation and guide you on the best steps to appeal a denial, maximizing your chance to have your eyelid surgery covered by insurance.
Your Path to Restored Vision and Confidence
The journey toward clearer vision and renewed confidence doesn’t have to be overwhelming. Whether you’re hoping to get eyelid surgery covered by insurance or exploring cosmetic options, Athena Plastic Surgery is here to guide you with expertise and care.

Your first step is a comprehensive consultation with a board-certified surgeon to get your questions answered and create a personalized plan.
During your consultation with Dr. Avron, we will assess your specific condition, examining your eyelids for issues like dermatochalasis or ptosis, and discuss how they impact your daily life. We will also review your medical history to ensure you are a good candidate for surgery and to provide the safest, most effective care.
Your goals matter tremendously to us. Whether your concerns are functional, aesthetic, or both, we want to understand exactly what you hope to achieve.
A crucial part of your consultation is determining medical necessity. If your eyelid issues affect your vision, there’s a good chance your eyelid surgery covered by insurance is possible. Dr. Avron’s extensive experience is key in making this determination and guiding you through the documentation process, including arranging tests and photos to build the strongest possible case.
Choosing a board-certified surgeon is essential. Dr. Avron’s Johns Hopkins training and over 15 years of experience mean you’re entrusting your care to an expert in both the medical and aesthetic aspects of eyelid surgery. We serve patients throughout West Palm Beach and Stuart, bringing advanced techniques and compassionate care to every consultation.
Your journey with us is a partnership. We are committed to helping you achieve your goals, whether that’s restoring clear vision, creating a more refreshed appearance, or both. Many of our patients are amazed by the life-changing results, finding renewed confidence that extends beyond improved vision. You can learn more here: Reaping the benefits of an eyelid lift in West Palm Beach.
Don’t let uncertainty about insurance keep you from exploring your options. If droopy eyelids are affecting your vision or confidence, you deserve to know what’s possible. We offer financing options and payment plans to make treatment accessible.
The clearer, brighter future you’re imagining is within reach. Schedule your blepharoplasty consultation to determine your options with us today. We’re here to help you see clearly and feel confident in your own skin again.