From CareCredit to Personal Loans: Financing Your Facelift
Facelift Surgery Is an Investment — Here’s How to Make It Work for Your Budget
How to finance a facelift is one of the most practical questions you can ask before moving forward with facial rejuvenation surgery. The good news: there are several proven ways to do it.
Quick answer — the most common ways to finance a facelift:
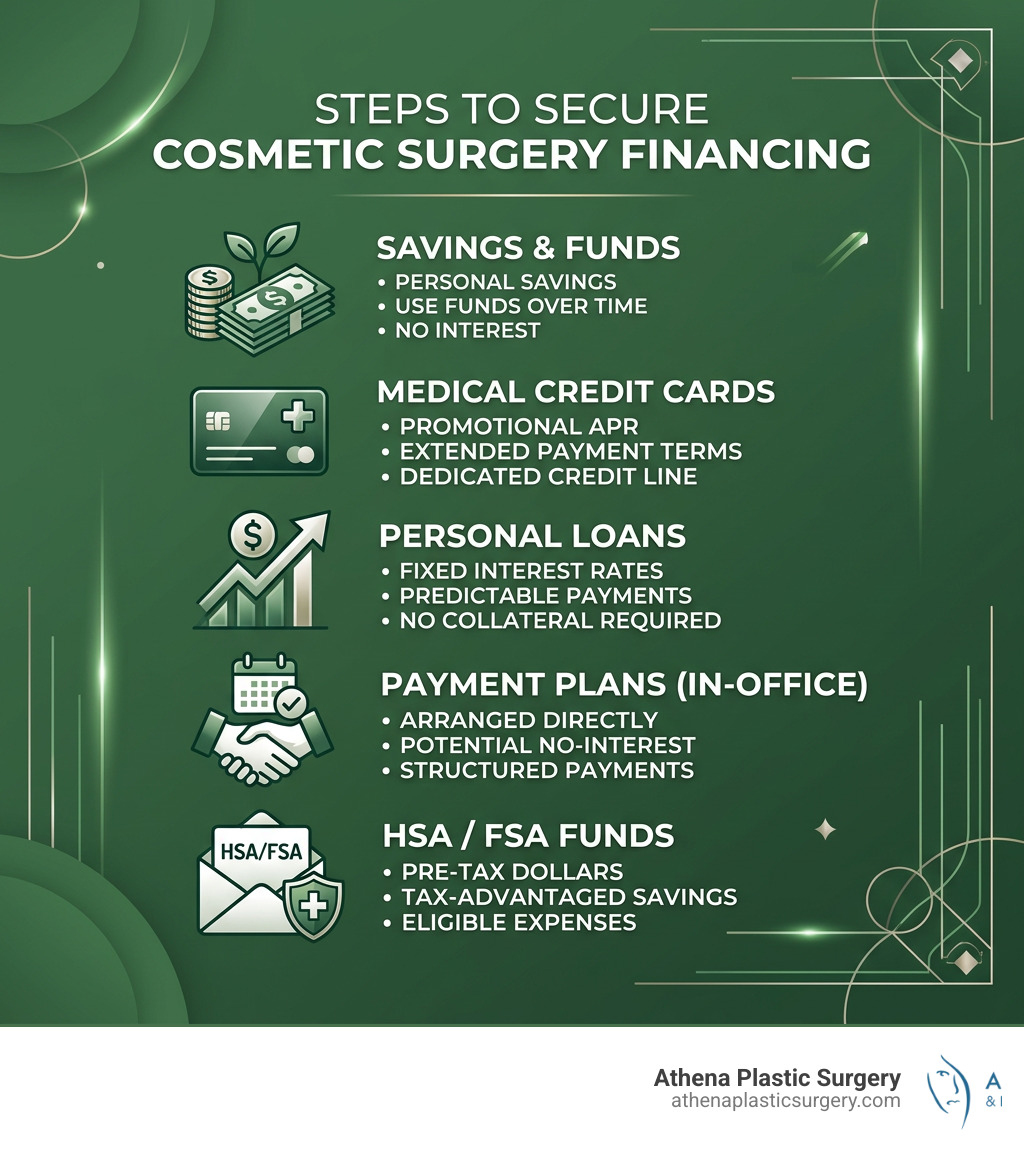
- Medical credit cards (like CareCredit or Alphaeon) — offer 0% promotional APR periods if paid within 6–24 months
- Personal loans — fixed interest rates, predictable monthly payments, no collateral required
- In-house payment plans — arranged directly with your surgeon’s office, often requiring a deposit upfront
- Traditional credit cards — best used with 0% intro APR offers and a clear payoff plan
- Personal savings or HSA/FSA funds — no interest, most straightforward option
- Specialized medical financing platforms — such as PatientFi or Cherry, designed specifically for elective procedures
Most health insurance plans do not cover facelift surgery, since it is considered an elective cosmetic procedure. That means the full cost comes out of pocket — and for many patients, that can feel overwhelming at first.
But with the right financing strategy, a facelift is more accessible than you might think. The key is understanding your options before your consultation, so you can make a confident, financially sound decision.
I’m Dr. Avron Lipschitz, a Board-Certified Plastic Surgeon with over 15 years of experience helping patients achieve their aesthetic goals — and I’ve guided countless patients through how to finance a facelift in a way that fits their life. In the sections below, I’ll walk you through every major payment option so you can find the approach that works best for you.
Understanding the Factors Influencing Facelift Costs
When you begin researching how to finance a facelift, the first thing you’ll notice is that there isn’t a single “sticker price.” Because every face is unique, every surgical plan is customized. At Athena Plastic Surgery, we believe in transparency, but we also know that a “one-size-fits-all” price doesn’t exist in high-end aesthetic medicine.
Several key components contribute to the final investment:
- Surgeon Expertise: A surgeon’s training and experience are paramount. Choosing a Johns Hopkins-trained expert like Dr. Avron ensures you are paying for technical precision and aesthetic artistry.
- Facility Fees: Surgery performed in an accredited surgical suite ensures the highest safety standards. These fees cover the specialized equipment, staff, and sterile environment required for your procedure.
- Anesthesia Costs: Whether you are undergoing a mini-lift or a deep plane facelift, a board-certified anesthesiologist or CRNA will be present to ensure your comfort and safety.
- Procedure Complexity: A Deep Plane Facelift Cost Guide 2025 will show that more advanced techniques, which reposition the deeper layers of the face for longer-lasting results, require more time and skill than a traditional skin-only lift.
- Geographic Location: Costs in South Florida, specifically in affluent communities like Stuart and West Palm Beach, reflect the high standard of care and expertise available in our region.
For a more detailed breakdown of what goes into these numbers, you can explore our Average Cost of Face Lift Surgery resource. While it may be tempting to “bargain hunt,” your face is not the place to cut corners. Financing allows you to choose the best surgeon rather than the cheapest one.

How to Finance a Facelift with Medical Credit Cards
If you prefer not to deplete your liquid savings, medical credit cards are one of the most popular ways to manage the cost of elective surgery. Unlike traditional credit cards, these are specifically designed for healthcare expenses and often come with “promotional periods.”
The most important thing to understand about these cards is deferred interest. Many plans offer 0% interest for 6, 12, 18, or even 24 months. However, if you do not pay the balance in full by the end of that period, the interest is often back-dated to the original purchase date at a very high rate (often 26% or higher).
Using CareCredit to Finance a Facelift
Care Credit is perhaps the most well-known name in the industry, with over 21 million accounts opened over the last three decades. Think of it as a dedicated health and beauty credit card.
- Reusable Credit: Once approved, you can use the card for follow-up treatments, skincare, or even other medical needs for your family or pets.
- Flexible Monthly Payments: It allows you to break down a large surgical fee into manageable monthly installments.
- Special Financing: For those looking into CareCredit for cosmetic procedures, the 0% APR promotional windows are a major draw for patients who have a clear plan to pay off the balance quickly.
Benefits of Alphaeon and PatientFi
While CareCredit is a giant in the field, other specialized lenders like Alphaeon Credit and PatientFi have gained massive popularity because they focus specifically on the “lifestyle” side of medicine.
- Alphaeon Credit: This card often provides higher credit lines—up to $25,000—which is ideal for comprehensive facial rejuvenation. They offer a wide array of “No Interest if Paid Within” and “Low interest” long-term options.
- PatientFi: This platform uses a “soft” credit pull for its initial offer, meaning it won’t hurt your credit score just to see what you qualify for. They pride themselves on high approval rates and a very user-friendly application process that focuses on making the procedure “attainable” rather than just “financeable.”
Comparing Personal Loans and Traditional Credit Cards
For some patients, a traditional bank loan or an existing credit card might be the most comfortable route. Each has its own set of pros and cons depending on your financial health and credit score.
| Feature | Personal Loan | Traditional Credit Card |
|---|---|---|
| Interest Rate | Fixed (usually lower than CCs) | Variable (often higher) |
| Repayment Term | Set period (e.g., 3–5 years) | Ongoing (revolving) |
| Collateral | None (Unsecured) | None (Unsecured) |
| Approval Speed | 1–3 business days | Instant (if already held) |
| Best For | Predictable monthly budgeting | Short-term bridge / Reward points |
When looking at Plastic Surgery Financing: Paying for Cosmetic Surgery | SoFi or similar lenders, you’ll find that personal loans are excellent for those who want a fixed end date for their debt. If you take out a three-year loan, you know exactly when your facelift will be “paid off,” and your monthly payment will never change.
Choosing the Best Way to Finance a Facelift
The “best” way is entirely subjective. If you have the cash but want to keep it in a high-yield savings account, a 0% APR medical credit card is a brilliant tool. However, if you need a longer time to pay—say, three to five years—a personal loan with a fixed APR (the national average for unsecured loans is currently around 12.40%) might be more responsible than a credit card that could jump to 25% interest after a year.
Avoiding Predatory Lenders and High Interest
In elective surgery, you may encounter “no credit check” lenders. Proceed with extreme caution. These often come with “origination fees” and interest rates that can exceed 35%. Always read the fine print. A reputable practice like ours will only partner with established, transparent financial institutions to ensure our patients are protected.
Alternative Ways to Pay for Your Procedure
Beyond loans and credit cards, there are several “self-funding” strategies that can make a facelift more affordable.
- Personal Savings: This is the only interest-free way to pay. Many patients choose to save for a year or two, essentially “paying themselves” the monthly installment before the surgery happens.
- HSA/FSA Eligibility: While a facelift is generally cosmetic, there are rare instances where a portion of the surgery (such as a blepharoplasty that corrects vision-impairing sagging) might be considered a qualified expense.
- Cherry Payment Plans: We also offer Cherry Payment Plans, a modern fintech solution that allows you to “Buy Now, Pay Later.” Cherry is incredibly popular because of its high approval speeds and range of payment plans that can fit almost any monthly budget.
Frequently Asked Questions about Facelift Financing
Does health insurance cover facelift surgery?
In almost every case, the answer is no. Insurance companies view facelifts as “elective cosmetic surgery,” meaning they are not medically necessary to maintain health. However, if you are undergoing reconstructive surgery following a trauma or a medical condition, some aspects might be covered. It is always best to check with your provider, but you should plan to self-finance your aesthetic rejuvenation.
Can I use an HSA or FSA for a facelift?
Standard IRS guidelines state that cosmetic surgery is not a qualified medical expense for tax-advantaged accounts. To use HSA or FSA funds, the procedure must meaningfully promote the proper function of the body or prevent/treat a disease. If your surgeon provides a “Letter of Medical Necessity” for a specific functional issue (like a brow lift to improve a restricted field of vision), you may be able to use these funds. Always consult with a tax professional first.
What if I have a lower credit score?
A lower credit score doesn’t necessarily mean you can’t finance your surgery. You might consider:
- A Co-signer: Having a spouse or family member with stronger credit co-sign for a medical loan can drastically improve your approval odds and interest rate.
- Specialized Lenders: Some companies specifically look at factors beyond just a FICO score.
- Building Credit: Delaying surgery by six months to pay down existing debt can save you thousands in interest later.
Conclusion
At Athena Plastic Surgery, we believe that everyone deserves to feel confident in their own skin. Dr. Avron and our entire team in Stuart and West Palm Beach are dedicated to providing not just world-class surgical results, but a compassionate and transparent experience from the first phone call to the final follow-up.
Investing in yourself is a big decision, but it shouldn’t be a stressful one. Whether you choose Financing through CareCredit, a personal loan, or a “Buy Now, Pay Later” plan with Cherry, we are here to help you navigate the process.
Ready to see what’s possible? Schedule your personalized consultation today and let’s create a plan that fits both your aesthetic goals and your financial reality.